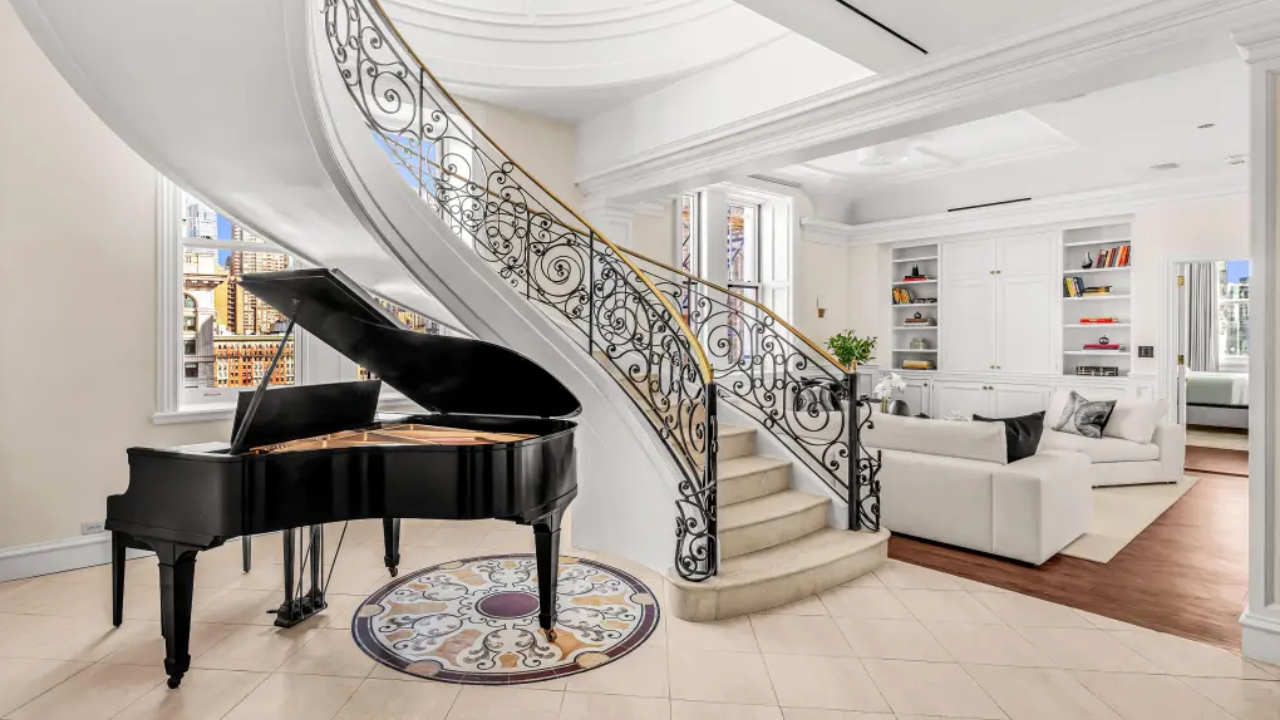
A sixty-four percent markdown from an initial asking price to a closed transaction value does not represent a negotiation concession. It represents a catastrophic failure of price discovery. When a gold-domed New York City penthouse listed at twenty-five million dollars ultimately clears at nine million dollars, the transaction exposes fundamental miscalculations in asset valuation, market psychology, and inventory liquidity within the ultra-prime residential sector.
Standard market commentary typically attributes such discrepancies to seller motivation, market softness, or macroeconomic shifts. These explanations substitute narrative for mechanics. To understand why an asset loses sixteen million dollars in value before finding a clearing price, one must examine the structural variables that govern high-end real estate: the psychology of anchoring, the compounding drag of holding costs, the extreme thinness of the buyer pool at the apex of the market, and the hidden architectural liabilities that deter rational capital. Meanwhile, you can read similar stories here: Inside the American Diesel Crisis Nobody is Talking About.
The Mechanics of Trophy Asset Anchoring
The genesis of a massive price correction lies in how ultra-prime properties enter the market. Sellers of unique, high-status real estate routinely abandon empirical comparable sales data in favor of aspirational pricing. This behavior is driven by endowment bias and the fallacy of uniqueness. Because a penthouse features rare architectural attributes—such as a gold dome, proprietary outdoor space, or historic provenance—stakeholders assume standard market capitalization rates do not apply.
This creates an artificial reference point. When a seller lists a property at twenty-five million dollars without transactional support from recent neighborhood comparables, they establish a dysfunctional anchor. Prospective buyers evaluate the property not on its fundamental utility or yield potential, but against that inflated benchmark. As time passes without offers, the listing suffers from market fatigue. Each month the property sits unsold, its perceived pedigree degrades. High-net-worth buyers interpret prolonged stagnation as a signal of latent defects, creating a toxic feedback loop where time on market depresses intrinsic value rather than establishing a premium. To see the bigger picture, we recommend the detailed report by Investopedia.
The Carrying Cost Equation and Velocity of Decay
Capital is not free, and holding an overvalued asset incurs severe operational friction. The carrying costs associated with a trophy New York City penthouse operate as a silent bleed on the owner's net present value.
Consider the fixed and variable liabilities of a multi-million-dollar urban residence:
- Property Taxes: Annual municipal assessments on luxury real estate scale rapidly, often running into six figures regardless of occupancy or rental yield.
- Common Charges and Maintenance: Buildings with unique architectural features, private elevators, or dedicated staff impose steep monthly operational fees to cover structural upkeep.
- Opportunity Cost of Capital: Capital locked in an illiquid, non-yielding asset misses alternative risk-adjusted returns in public markets, private equity, or fixed income.
- Financing Drag: If the asset is leveraged, debt service payments continue to accrue, converting an unrealized pricing error into an immediate cash flow drain.
When carrying costs exceed the projected appreciation rate of the asset, the seller enters a state of negative carry. As cumulative holding expenses mount, the seller's psychological resilience fractures. The tipping point arrives when the cost of retention surpasses the psychological barrier of accepting a steep nominal loss. At this juncture, the seller transitions from a discretionary market participant to a motivated liquidator, precipitating the price drop.
Liquidity Asymmetry at the Apex
The fundamental economic driver behind a sixteen-million-dollar write-down is liquidity asymmetry. In standard residential housing markets, buyer demand follows a normal distribution curve. As price tiers ascend, the buyer pool contracts exponentially.
At the nine-million-dollar threshold, a property appeals to a broad cross-section of domestic executives, successful entrepreneurs, and regional investors. At the twenty-five-million-dollar threshold, the addressable market shrinks to a micro-fraction of the global population—ultra-high-net-worth individuals whose purchasing decisions are governed by strict portfolio diversification rules and liquidity management.
When a property is priced out of its natural liquidity tier, transaction velocity drops to zero. A thin buyer pool means zero competitive tension. Without competing bids, sellers lose pricing power entirely. When the asset finally adjusts to nine million dollars, it re-enters a liquid tier where multiple buyers possess the capital and inclination to transact. The massive price drop was not a reflection of sudden value destruction, but the distance required to travel from a vacuum of demand to a zone of market clearing liquidity.
Structural and Architectural Friction
Beyond price and liquidity, extreme discounts reveal physical or legal liabilities that initial marketing materials obscure. A gold dome or historic facade may provide aesthetic distinction, but it often conceals severe operational liabilities.
Prospective buyers at the ultra-prime level conduct rigorous due diligence, examining physical infrastructure, board governance, and capital improvement reserves. Properties that suffer historic write-downs frequently share specific architectural friction points:
- Layout Inefficiencies: Historic or heavily stylized floor plans that prioritize dramatic vertical space over functional living areas, reducing usable square footage.
- Mechanical Deficits: Outdated HVAC systems, insufficient electrical capacity, or complex roof maintenance requirements that present future capital expenditure nightmares.
- Building Financial Health: High building debt, underfunded capital reserves, or restrictive co-op/condo board regulations that limit renovation flexibility or subletting rights.
When these underlying friction points are factored into a sophisticated buyer's underwriting model, the initial twenty-five-million-dollar valuation collapses. The nine-million-dollar closing price reflects the true net present value after discounting for impending capital expenditures and functional obsolescence.
Strategic Allocation Rule
Acquirers and developers operating in high-value urban real estate must abandon reliance on speculative comparables and emotional branding. Valuation must be anchored to liquidity thresholds and net carrying drag rather than architectural novelty. When an asset deviates from market-clearing fundamentals by more than twenty percent, prolonged resistance accelerates value destruction. The optimal strategic response to structural mispricing is immediate recalibration to the true liquidity band, preventing the severe capital erosion that accompanies prolonged market stagnation.