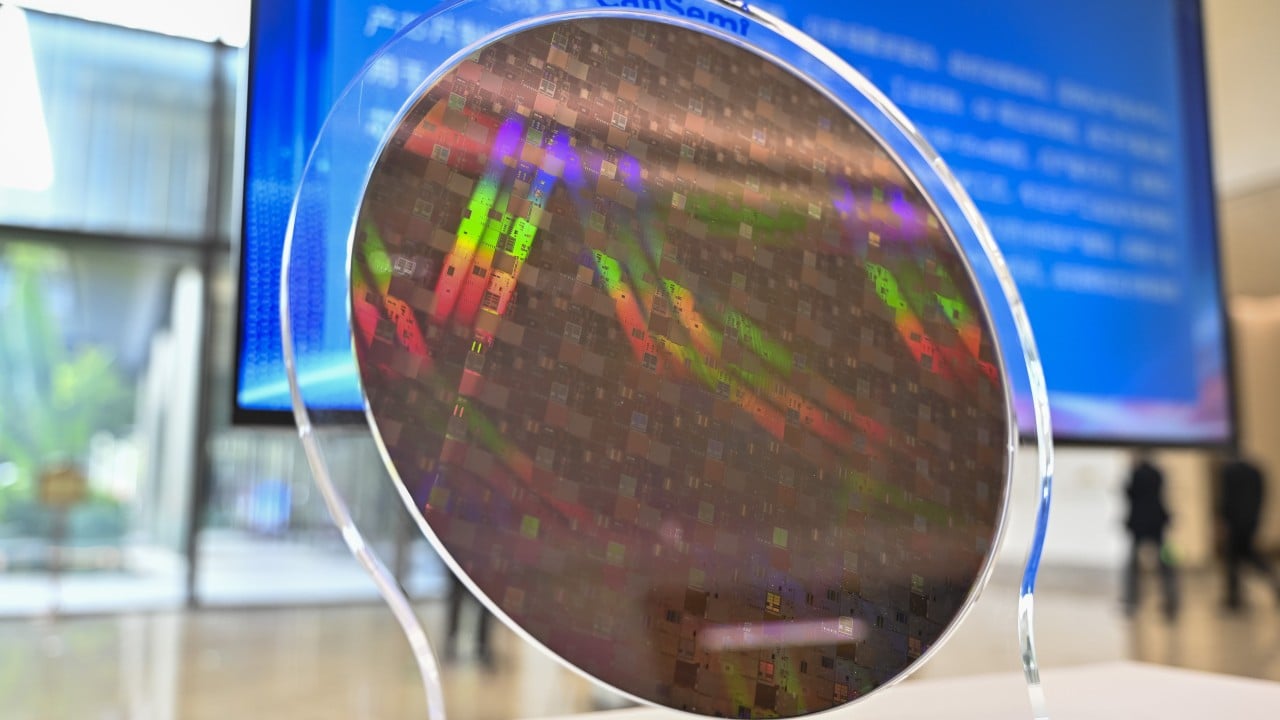
Wall Street and the financial press are popping champagne because CanSemi just saw its initial public offering oversubscribed by a staggering 2,360 times. The narrative being spun across every major terminal is dead simple: retail and institutional capital are flooding into Chinese semiconductor foundries, fueled by an insatiable domestic appetite for artificial intelligence hardware and a desperate bid for self-reliance against western trade restrictions.
It makes for a fantastic headline. It is also entirely detached from economic reality.
I have spent decades watching state-backed capital chase shiny objects in manufacturing hubs from Shenzhen to Austin. I have seen syndicates throw hundreds of millions at equipment orders while ignoring the fundamental unit economics of silicon fabrication. A 2,360-fold oversubscription rate is not a testament to industrial genius or an unstoppable AI boom. It is a symptom of a distorted asset market suffering from chronic capital misallocation, where speculative frenzy masquerades as technological sovereignty.
Let us look past the euphoria and dismantle the lazy consensus.
The Liquidity Trap Disguised as Industrial Policy
The core fallacy underpinning the celebration of CanSemis debut is the belief that throwing cash at a foundry solves the engineering bottlenecks of modern node scaling. Capital expenditure does not equal capability.
When a share offering is oversubscribed by thousands of times, it means dry powder is trapped in a domestic financial system with precious few high-yield alternatives. China's macroeconomic slowdown has left institutional investors and retail speculators clutching excess liquidity. With property markets cooling and foreign capital looking hesitant, government-backed tech plays become the only game in town.
CanSemi is catching this wave not because its proprietary architecture is poised to dethrone industry leaders, but because it is positioned as a proxy for national ambition. Money is rushing in because investors are buying a political hedge, not an earnings stream.
[Capital Surplus] -> [Blocked Foreign/Property Outlets] -> [State-Adjacent Tech IPOs] -> [Stratosperic Oversubscription]
This dynamic creates a dangerous illusion. When valuations disconnect entirely from wafer yields, defect densities, and capital depreciation cycles, you stop building a sustainable industrial base and start inflating a speculative bubble. Fab economics are brutal. A billion dollars in funding vanishes into lithography machines and cleanroom maintenance before you print a single commercially viable chip.
The Maturity Myth and the AI Hardware Chasm
The mainstream coverage breathless links CanSemi's financial windfall directly to the artificial intelligence boom. This is where the analysis falls apart completely.
AI acceleration requires advanced packaging, extreme ultraviolet lithography, and high-bandwidth memory integration operating at sub-7-nanometer thresholds. Foundries focusing on mature nodes—legacy silicon typically sitting at 28 nanometers and above—play a vital role in automotive components, power management ICs, and IoT sensors. They do not power high-end language models or neural network training clusters.
Conflating mature node foundry demand with the generative intelligence gold rush is sloppy thinking.
| Metric | AI Hardware Reality | Mature Node Foundry Reality |
| :--- | :--- | :--- |
| *Node Target* | 3nm to 7nm | 28nm to 180nm+ |
| *Primary Driver* | Large Language Models, Neural Nets | Automotive, Appliances, Power ICs |
| *Bottleneck* | EUV Access, Advanced Packaging | Overcapacity, Margin Compression |
| *Capital ROI* | High Margin, High Risk | Commodity Pricing, Volume Dependent |
| *Financial Health* | Driven by Enterprise Compute Budgets | Vulnerable to Price Wars |
| *Geopolitics* | Chokepoint Technology | Commoditized Manufacturing |
If you look at the actual fabrication lines filling up order books across the region, they are largely wrestling with fierce margin compression. As more state-backed competitors spin up similar mature node fabs to chase independence metrics, the market faces a looming threat of commoditization. Everyone is building the exact same foundational capacity, driving down average selling prices while input costs for raw silicon and specialized gases remain sticky.
When the dust settles on these record-breaking order books, the survivors will not be the ones with the most enthusiastic retail investors. They will be the ones with structural yield advantages and long-term enterprise supply agreements that survive margin crunches.
The Cost of Distortion
Admitting the downside of this heavy-handed capital infusion is uncomfortable for cheerleaders of state-led industrial policy, but it is necessary. By artificially inflating valuations through hyper-subsidized share allocations, markets fail to price risk correctly.
When failure is insulated by state backing and speculative hype, companies lose the evolutionary pressure that forces operational excellence. Real engineering breakthroughs come from solving margin constraints under harsh commercial realities, not from basking in the glow of a media cycle celebrating an oversubscribed ticker symbol.
Stop treating financial froth as proof of technological dominance. The real test for any foundry begins long after the closing bell of its market debut, down on the cleanroom floor where physics does not care about your subscription ratio.
Check your portfolio assumptions, ignore the hype metrics, and watch who actually masters the yield curve when the cheap money dries up.