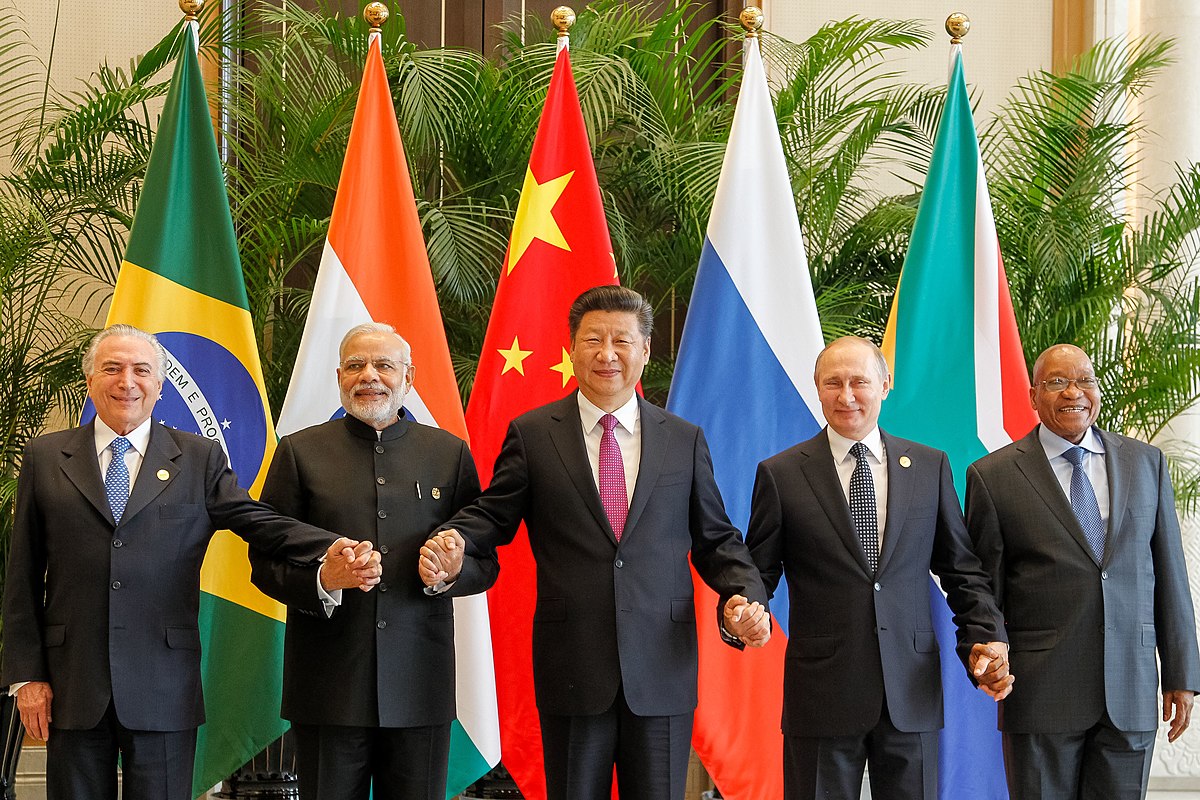
Every six months, the financial commentariat dusts off the same tired script. A summit happens, handshakes are exchanged, and a dozen op-eds appear warning that the dollar's monopoly is finished because a bloc of developing nations is about to launch a rival reserve currency.
It is lazy analysis built on a fundamental misreading of what the bloc actually wants.
I spent a decade advising sovereign wealth funds on cross-border liquidity management. I have watched central bankers sweat over secondary sanctions while trying to settle basic energy trades. The consensus narrative in Washington and London assumes the coalition centered around Beijing and Moscow is trying to build a better SWIFT, a cleaner IMF, and a shiny new greenback killer.
They are doing none of those things.
The strategy is not to conquer the global financial architecture. The strategy is to build a bomb shelter.
The Currency Myth That Refuses to Die
Let us start with the primary delusion: the imminent arrival of a unified BRICS currency. Financial journalists love this trope because it sounds like a geopolitical thriller. It makes for great television. It is also entirely detached from economic reality.
A reserve currency requires two things that this coalition structurally refuses to provide: deep, liquid, open capital markets and a political authority that willing creditors trust implicitly. You cannot anchor a global currency to an opaque basket of managed floats and authoritarian capital controls. If you hold US Treasury bonds, you may dislike American foreign policy, but you know you can liquidate billions of dollars at three in the morning with a phone call. Try doing that with a newly minted multilateral unit backed by a committee of central bankers who disagree on everything from border disputes to interest rate policy.
The members know this. Beijing knows this. Moscow knows this. New Delhi certainly knows this, having spent years refusing to accumulate surplus rubles or yuan that it cannot freely convert.
When leaders talk about expanding economic ties, they are not designing a euro for the Global South. They are constructing bilateral plumbing. They are laying down bypass routes for trade settlement in local currencies—rupees, yuan, dirhams, reals—specifically designed to function outside the reach of the Office of Foreign Assets Control.
Weaponized Interdependence and the Real Motive
To understand why the coalition is expanding its membership to include major energy exporters and regional heavyweights, you have to look at the weaponization of the global financial system over the past decade.
When the West froze hundreds of billions of dollars in Russian central bank reserves overnight, it crossed a Rubicon. It sent an unambiguous signal to every capital city outside the Western alliance: if your foreign policy diverges from Washington's, your national savings can be confiscated with the click of a mouse.
That single event did more for de-dollarization than a hundred academic conferences. It terrified surplus nations.
The expansion into a larger bloc is not about projecting ideological solidarity. It is about aggregating commodity power and consumer markets to create a self-contained economic loop that is immune to Western coercion. When Saudi Arabia, the United Arab Emirates, and Iran sit at the same table with the world's largest manufacturing powerhouse and its largest agricultural and energy producers, you are looking at an autarkic safety net.
They are not trying to replace the dollar as the global invoice currency for a Swiss cheesemaker in Bern. They are ensuring that if a trade dispute erupts tomorrow, they can keep buying oil, shipping steel, and settling accounts without touching a single correspondent bank in New York.
The Structural Vulnerability Nobody Admits
My contrarian take comes with a caveat, because intellectual honesty requires admitting the flaws in your own thesis. This bypass architecture is messy, inefficient, and expensive.
Trading oil in yuan or rupees instead of dollars introduces massive currency risk, transaction friction, and liquidity traps. If Beijing accumulates billions of rupees from Indian trade, what exactly is it going to buy in Delhi of equivalent value without imposing heavy economic distortions? The answer is: not much. That is why bilateral currency swaps often stall out after the initial political ribbon-cutting ceremony.
Running a global trade empire on bilateral barter and messy local-currency invoicing is like trying to run modern air traffic control with signal flags. It is slower. It creates trade imbalances that are painful to resolve.
Yet, for these governments, inefficiency is a cheap tax to pay for sovereignty. They would rather absorb the friction of fragmented markets than face the existential risk of financial decapitation during the next geopolitical crisis.
Stop Asking the Wrong Question
The mainstream financial press keeps asking: "When will the new currency dethrone the dollar?"
That is the wrong question. It betrays a total misunderstanding of monetary history. Empires do not lose reserve status overnight because a rival launches a better token. They lose it slowly, inch by inch, as secondary players build alternative corridors because the core infrastructure becomes too politically toxic to trust.
The bloc is not building a throne. They are building an exit door. And every time a new sanctions package is signed, more nations walk through it.